Coach Sales Climb 16% While Kate Spade Declines 10%, Prompting the Group to Raise Its Fiscal 2027 Outlook
Tapestry has started its fiscal 2027 year with another strong quarter, reporting revenue of $1.89 billion, up 12% on a comparable pro forma basis, as continued momentum at Coach more than offset declining sales at Kate Spade. The New York-based fashion group also raised its full-year outlook after delivering stronger profitability and attracting millions of new customers.
For the quarter ended September 26, 2026, reported revenue increased 11%, while the 12% pro forma growth figure excludes Stuart Weitzman from the prior-year comparison following its sale in August 2025. Net income rose 31% to $360 million, while adjusted earnings per share increased 32% to $1.82. Adjusted operating margin expanded to 23.2%, compared with 20.9% a year earlier.
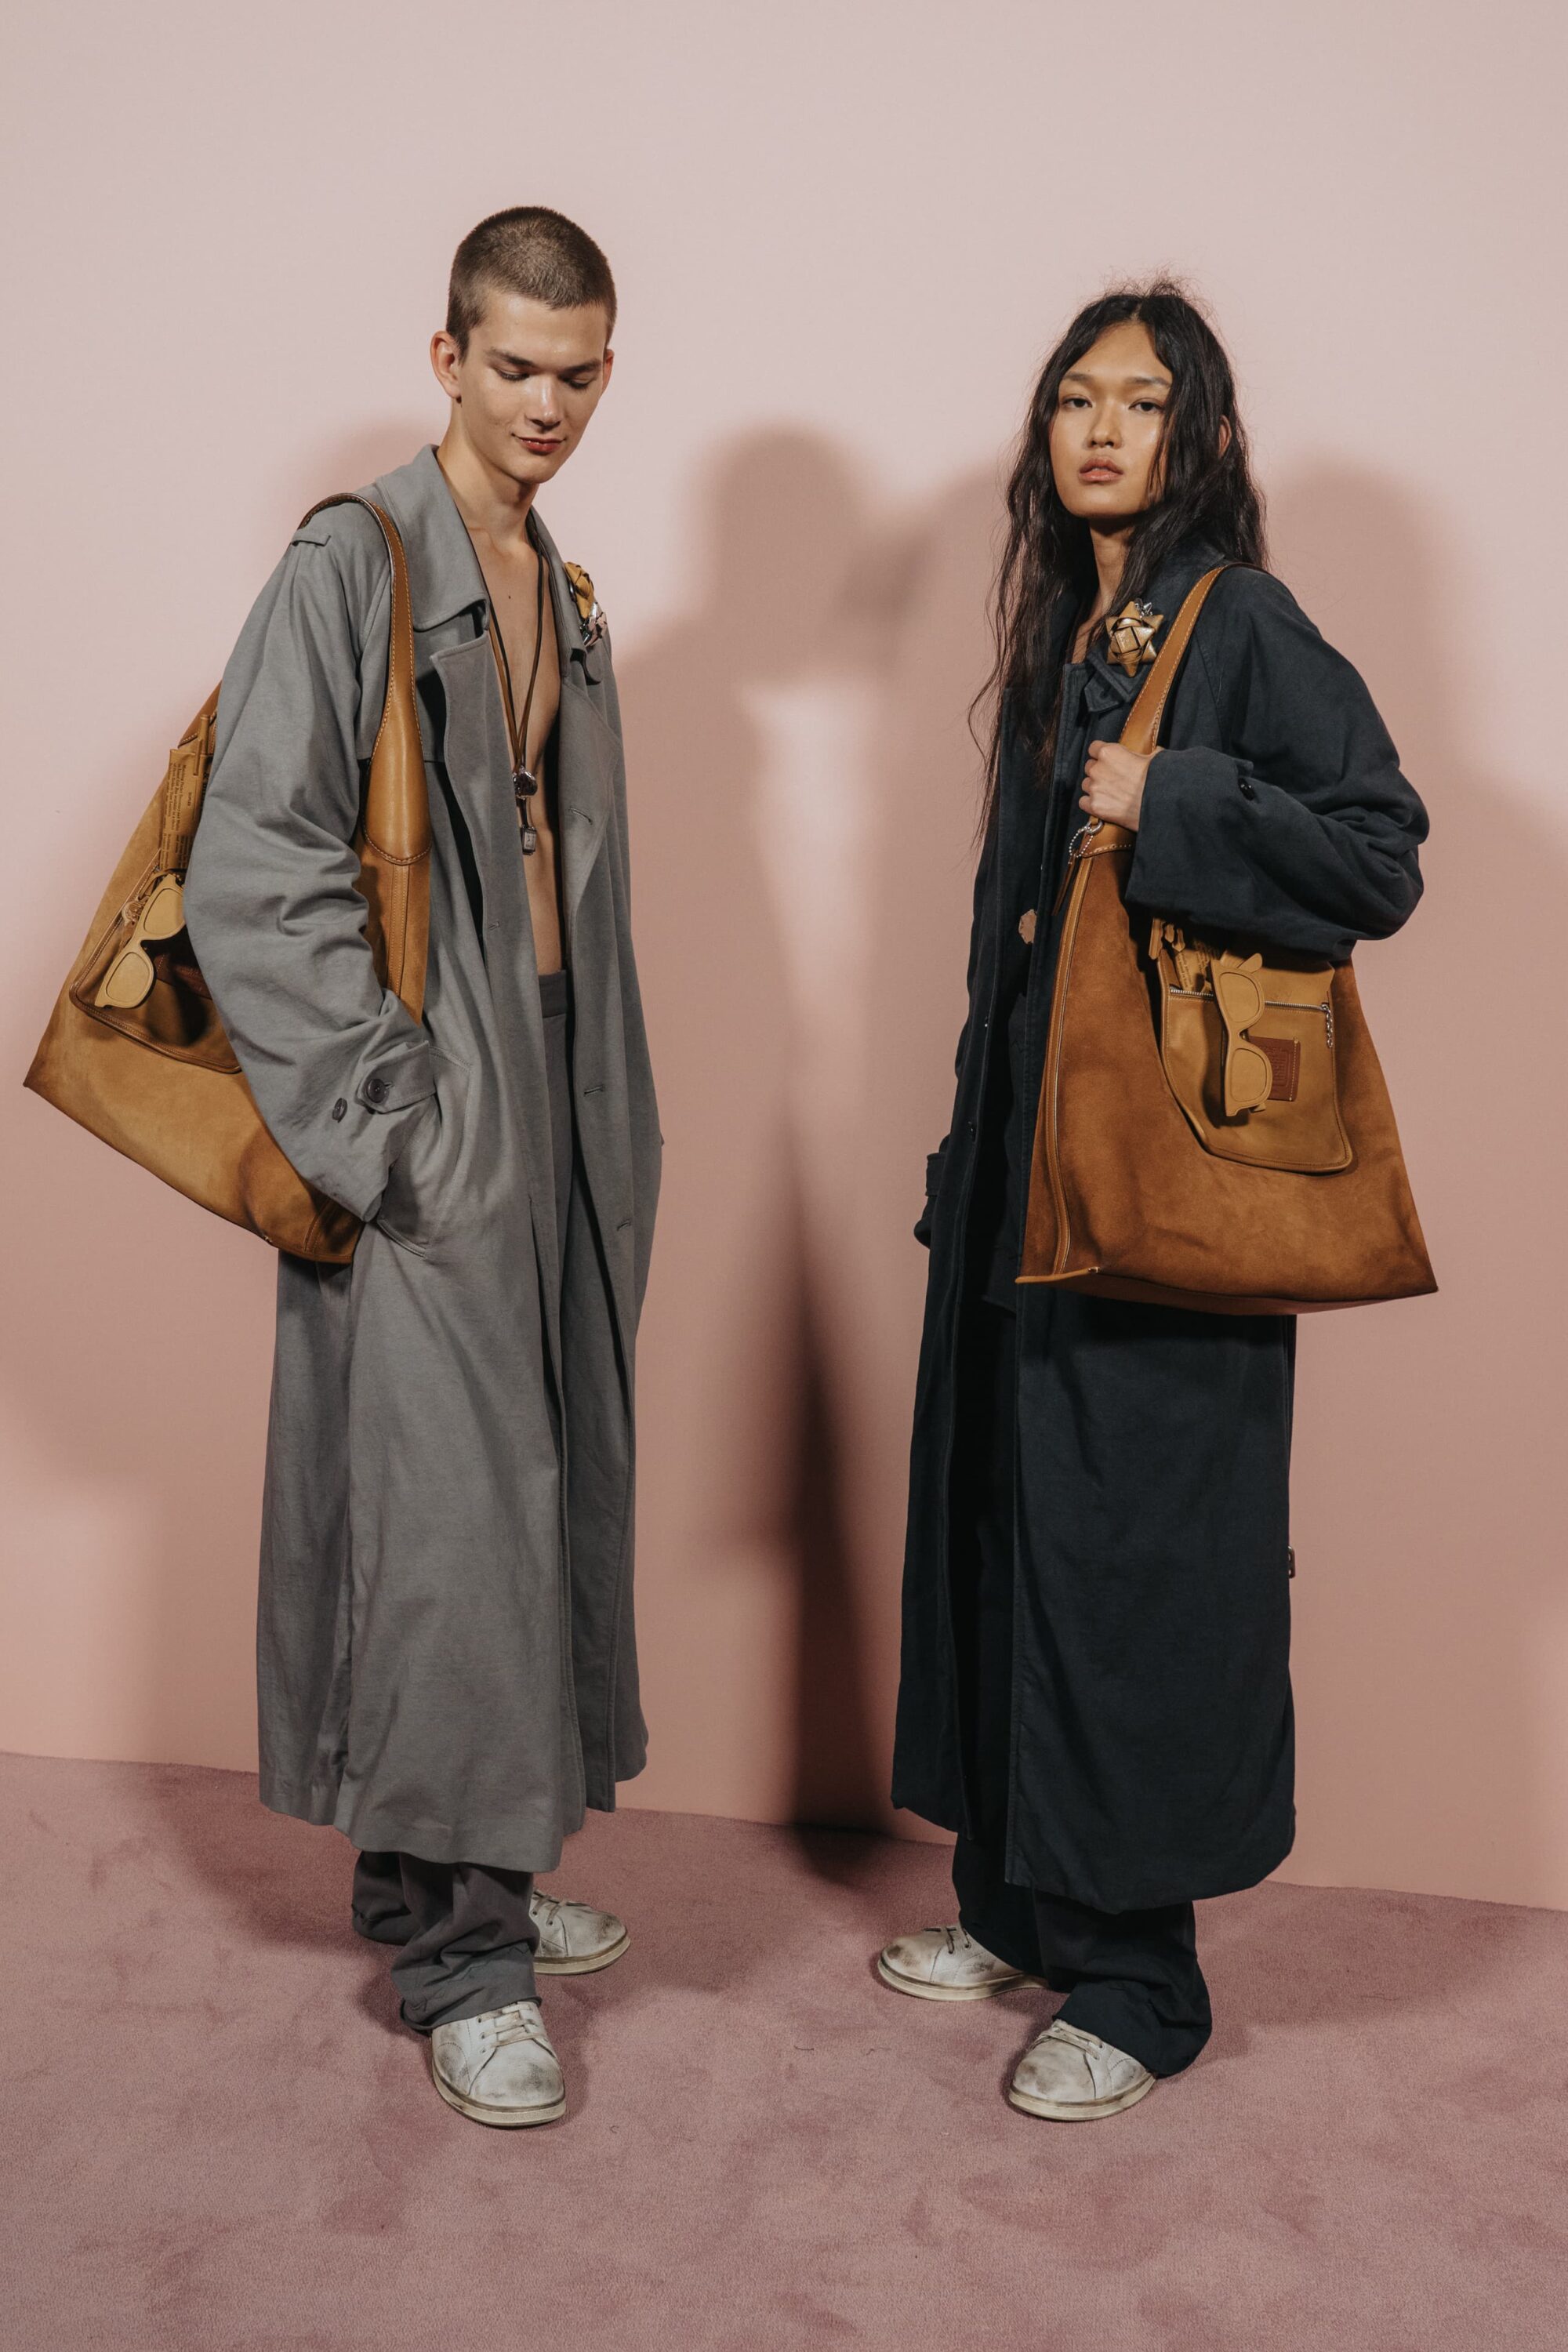
Coach remains the principal engine of Tapestry’s growth. The brand generated $1.66 billion in quarterly revenue, an increase of 16%, continuing a period of strong demand for its handbags and leather goods. Coach’s performance is particularly notable given the broader luxury industry’s uneven recovery, with the American accessories house continuing to attract customers while increasing the prices consumers pay for its products.
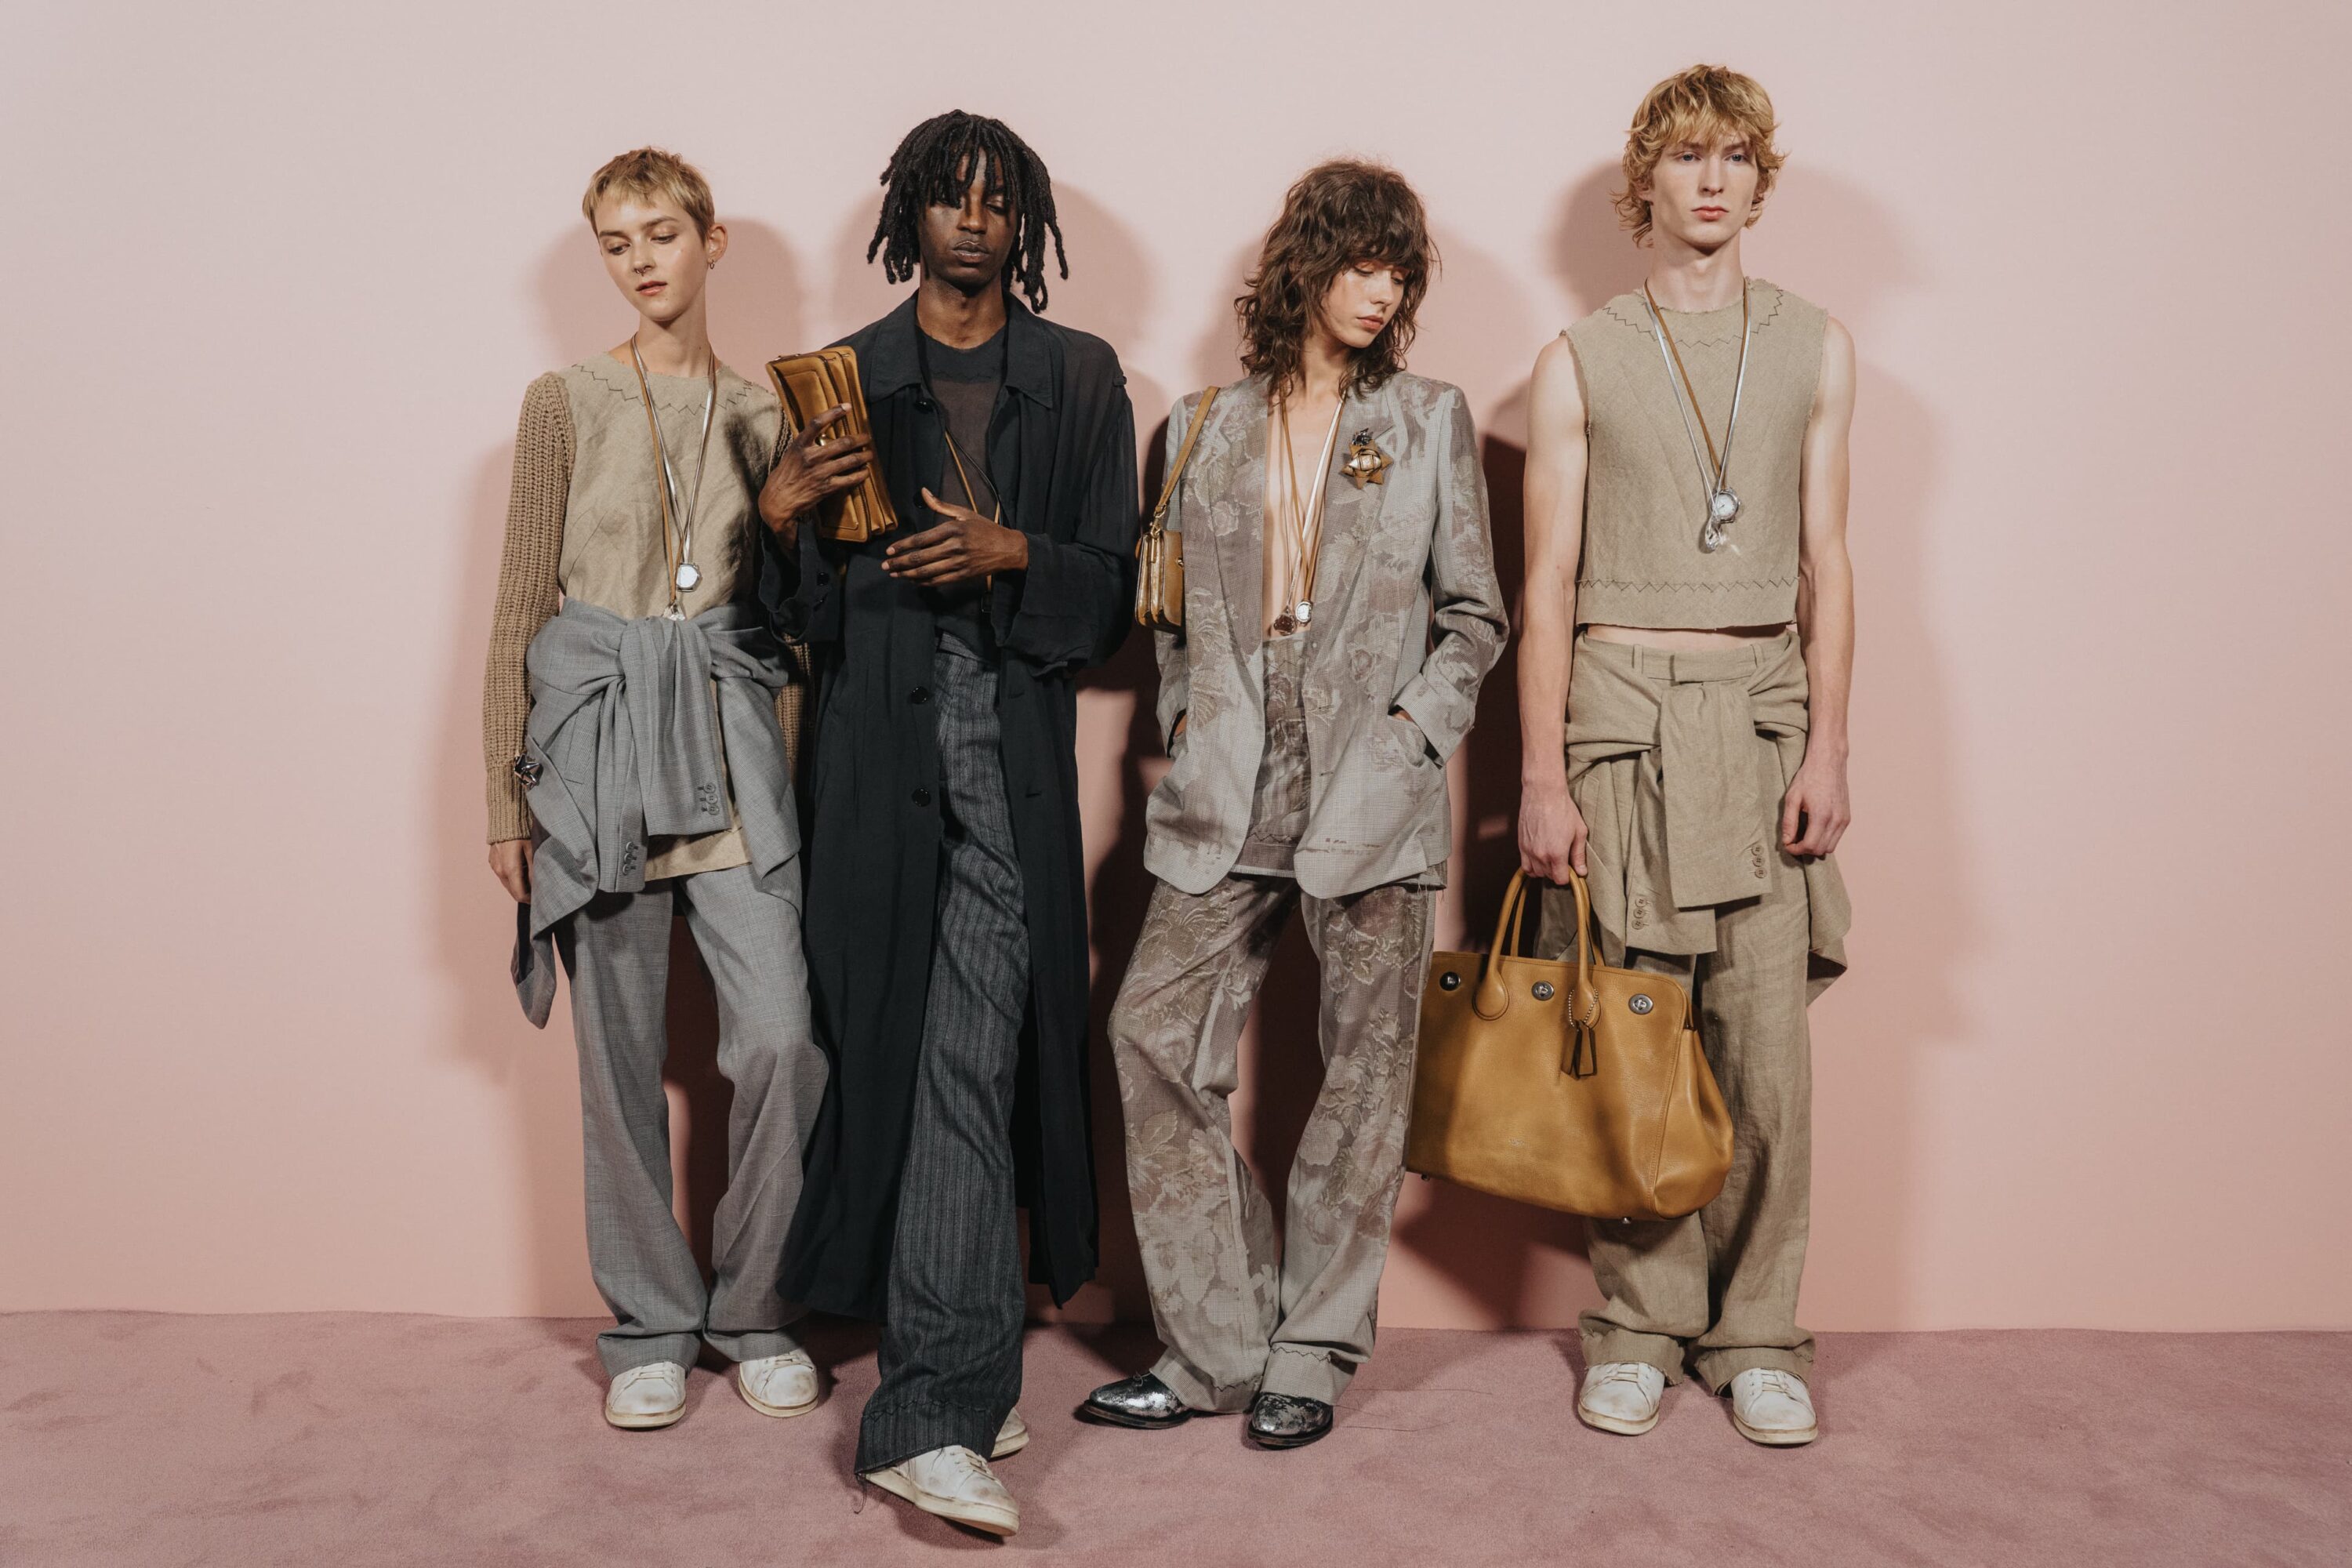
Average unit retail prices for Coach handbags rose at a low-double-digit rate, accompanied by low-single-digit growth in unit sales. The combination suggests that customers are responding to the brand’s product offering even as its average selling prices increase. Rather than relying exclusively on selling more handbags, Coach is generating additional revenue through a stronger product mix and higher realized prices.
The brand’s geographic performance was equally encouraging. Coach revenue increased 7% in North America, its largest market, while international sales grew 30%. The results suggest that the brand’s recent momentum is extending beyond its established American customer base, providing Tapestry with a broader foundation for future growth.
Kate Spade presents a different picture. Revenue at the brand declined 10% to $233 million as Tapestry continues efforts to strengthen its positioning and rebuild demand. The contrast between the two houses remains one of the group’s most important challenges: Coach has developed a clear commercial identity that is attracting new customers, while Kate Spade has yet to demonstrate a comparable recovery.
The difference is also visible in profitability. Coach generated $590 million in operating income during the quarter, while Kate Spade recorded an adjusted operating loss of $6 million. The figures underline how much of Tapestry’s current financial strength depends on Coach and how important Kate Spade’s eventual improvement will be to the group’s longer-term ambitions.
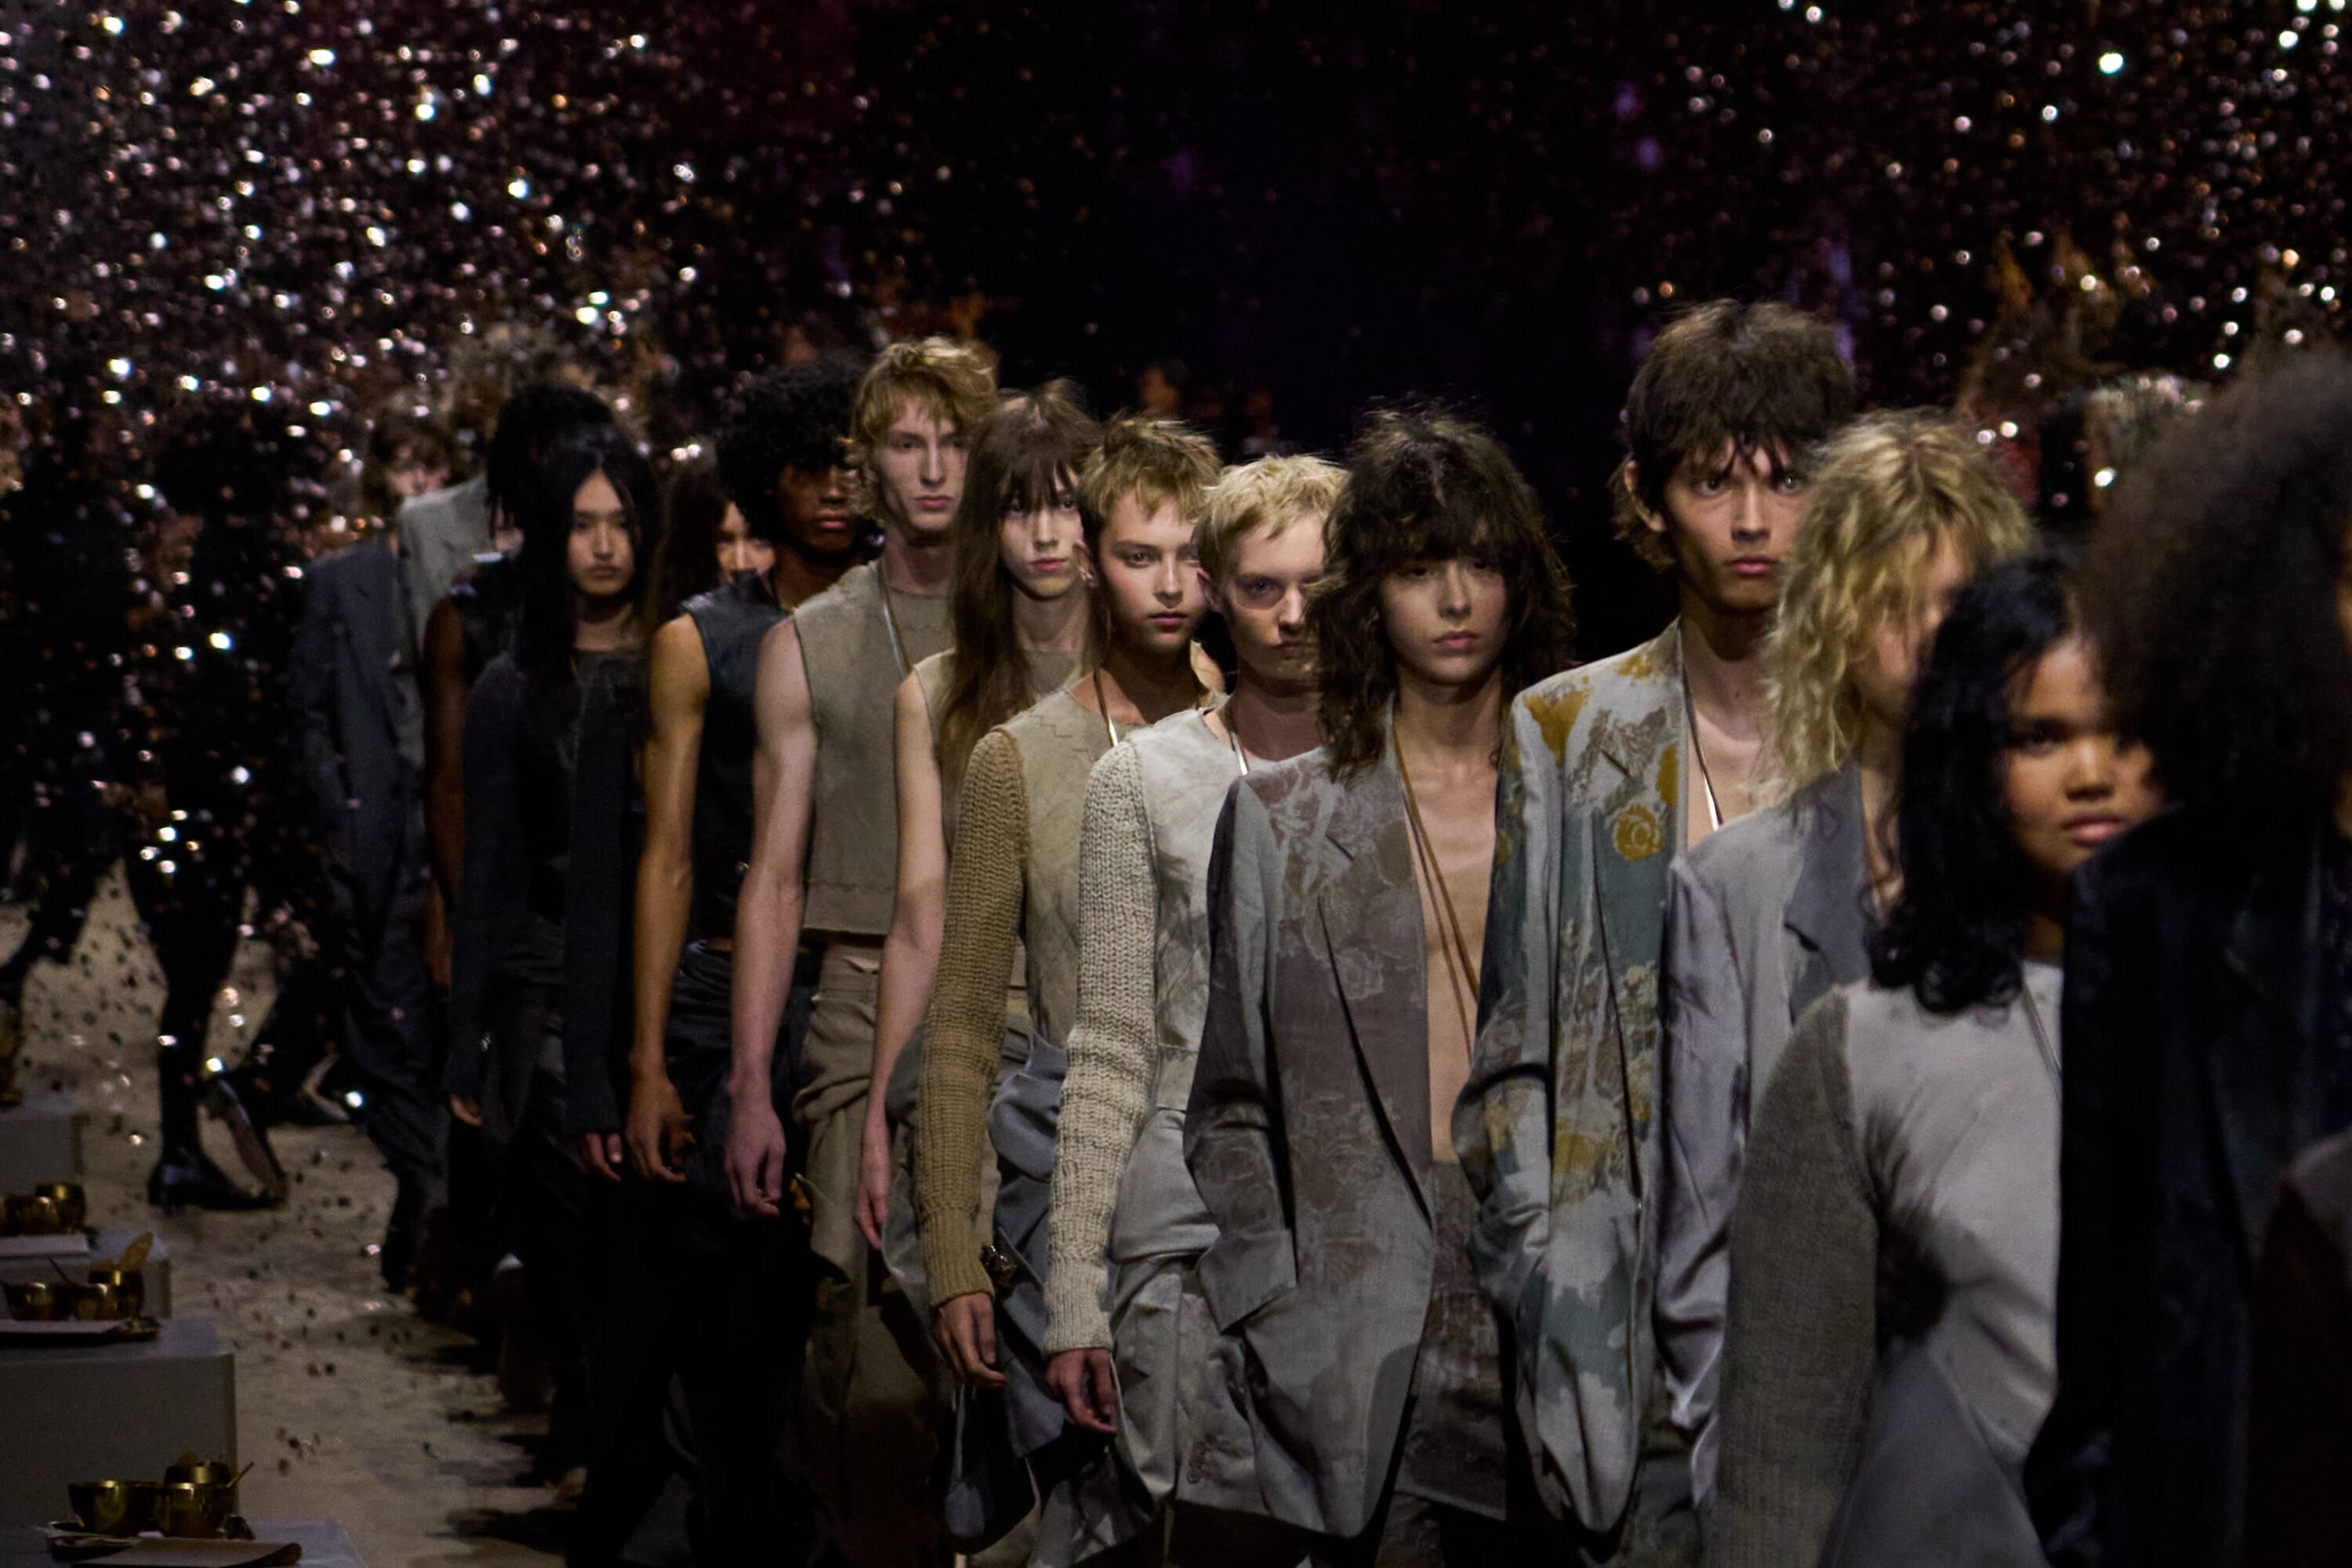
Tapestry’s customer acquisition figures offer another perspective on Coach’s success and the group’s broader strategy. The company welcomed approximately 2.6 million new customers globally during the quarter, with Generation Z accounting for about 35% of those additions. Demand from existing customers also increased, suggesting that the group’s growth is not coming solely from first-time purchases.
The ability to attract younger consumers has become particularly important in a luxury market where many established brands are struggling to maintain engagement with aspirational shoppers. Coach’s combination of recognizable design, accessible luxury positioning and a renewed emphasis on product desirability appears to be resonating with a generation whose purchasing habits are increasingly important to the industry’s future.
Geographically, Tapestry recorded particularly strong growth in Asia. Revenue in Greater China increased 39% on a constant-currency basis, reaching $385 million, while Europe grew 22% to $151 million. North American revenue increased 4% to $1.11 billion, reflecting a more mature but still expanding market.
The Greater China performance stands out against the challenges reported by several European luxury groups, many of which continue to face weaker demand in the region. Although Tapestry operates at a different price position from the largest European luxury houses, its results demonstrate that consumer appetite for fashion accessories remains substantial when the product and value proposition connect with shoppers.
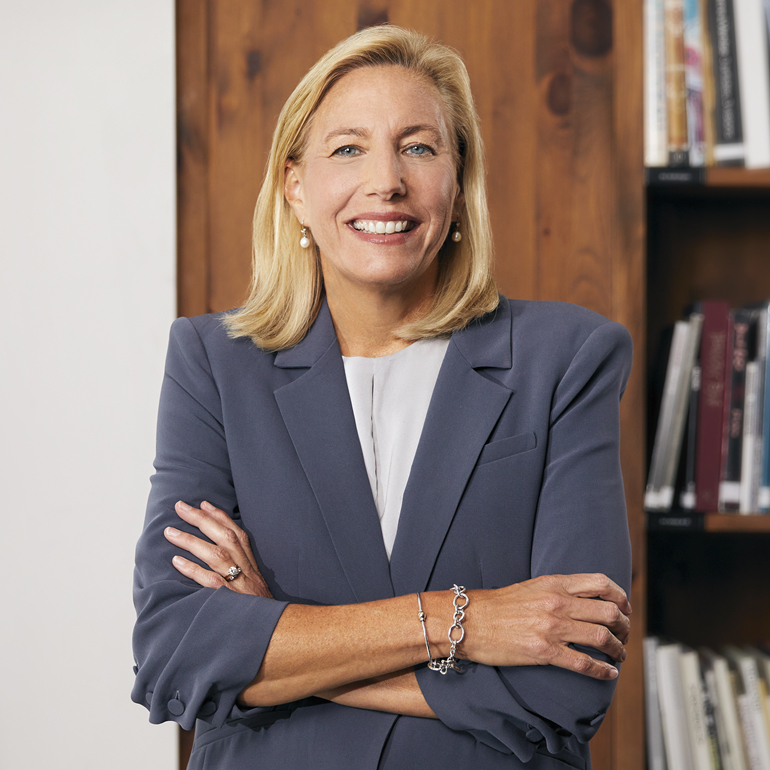
“Our first quarter marked a powerful start to the year, with revenue, margin, and earnings growth ahead of expectations and strength around the world,” said Joanne Crevoiserat, Chief Executive Officer of Tapestry. “Our Amplify strategy continues to bring new consumers to our brands through our distinctive combination of creativity, craftsmanship, and value.”
The group’s Amplify strategy emphasizes stronger consumer relationships, fashion innovation and improved customer experiences. Its early results have been particularly visible at Coach, where product development and brand positioning have helped support both customer acquisition and higher average handbag prices.
Tapestry also reported a 9% increase in direct-to-consumer revenue on a pro forma basis, with store sales growing at a low-double-digit rate and digital sales increasing at a mid-single-digit pace. Wholesale revenue rose approximately 30%, supported primarily by international markets.
Profitability improved alongside revenue. Adjusted gross margin reached 78.7%, an increase of 220 basis points from the previous year, supported by operational improvements and favorable effects from tariffs and foreign exchange. Adjusted operating income increased 24% to $439 million, demonstrating that the company’s sales growth is translating into stronger earnings.
Following the quarter, Tapestry raised its fiscal 2027 revenue forecast to between $8.5 billion and $8.6 billion, representing expected constant-currency growth of approximately 6% to 7%. The previous outlook called for revenue between $8.4 billion and $8.5 billion.
The company also increased its adjusted earnings-per-share forecast to $8.25 to $8.35, up from $7.80 to $7.90, and now expects operating margin to expand by approximately 100 basis points for the full year, twice its previous projection.
Tapestry plans to return approximately $2 billion to shareholders during fiscal 2027 through dividends and share repurchases, including $1.7 billion in anticipated buybacks.
The raised outlook reflects confidence in Coach’s ability to sustain its momentum, although the continued weakness at Kate Spade remains an important qualification. Tapestry has demonstrated that an American accessories brand can deliver substantial growth in a difficult luxury environment, but the next test will be whether that success can be sustained while its second fashion house finds a clearer path forward.
For now, Coach is doing considerably more than carrying its share of the business. Its performance is helping redefine Tapestry’s growth prospects and offering an instructive example of how product desirability, customer engagement and pricing discipline can work together, even when the wider fashion market is moving at very different speeds.